Short answer: memo out is your asset sitting in someone else's safe. Memo in is someone else's asset sitting in yours. The first is unsecured credit you have extended; the second is a liability you are storing, insuring and expected to account for. Most jewelry businesses run one of these properly and the other from memory — and it is almost always memo in that gets the memory.
The same transaction, from both ends
A parcel leaves a dealer and arrives at a retailer. Nothing about the goods changes. Everything about the position does.
For the dealer, the parcel is still an asset on their books, now outside their physical control, with a clock running on it and no security over it unless they filed for one. For the retailer, the parcel is stock they can sell but do not own, occupying case space and insurance capacity, creating an obligation to report and pay on sale and to return what does not sell.
The trade uses one word for both, which is part of why businesses end up with two different standards of record-keeping for what is structurally the same event.
Memo out: credit you extended without a loan agreement
Sara Yood at the Jewelers Vigilance Committee describes the supplier's position exactly: "Most of the risk falls on the supplier, who is in effect lending the merchant the agreed upon cost of the goods."
What that means operationally:
The asset stays yours, and stays on your books. Under US GAAP the consignor retains control and the goods remain on the consignor's balance sheet until control transfers. Revenue is not recognised on delivery — it is recognised when the product sells to a final customer, a specified period expires, or the goods are lost or damaged.
You are exposed to your customer's creditors, not just your customer. Most memo arrangements are consignments under UCC Article 9, which means the merchant is deemed to have the same rights in the goods as you do while it holds them. Unperfected, you rank as a general unsecured creditor if they fail. Perfecting by filing a UCC-1 before delivery is the step that changes that.
Your discipline is aging. Days out per line, grouped by counterparty, with thresholds that trigger a call and a decision. See memo aging for the routine.
Your evidence problem is substitution and loss. Certification and tagging on significant stones, photographs of what went out, and a signed record of what was received.
Memo in: a liability that looks like stock
This is the side that goes wrong quietly, because everything about it feels like inventory. It sits in your case. Your staff sell from it. Your POS rings it up. It photographs like stock and it displays like stock.
It is not stock.
It does not belong in your inventory valuation. The goods remain the consignor's until control transfers. If you carry memo-in goods in your stock value, you overstate the asset — and every ratio built on that number goes with it. Your inventory turn looks worse than it is because the denominator is inflated. Your GMROI looks worse for the same reason. Your insurance schedule may be wrong in both directions at once. And if you are borrowing against inventory, you are borrowing against goods you do not own.
You are responsible for it physically. Custody brings liability for loss, theft and damage, and the allocation depends entirely on the agreement. The common failure is that many memo agreements address none of this — they cover price, quantity and the return window and leave risk of loss implied. Both parties can genuinely hold an insurable interest in the same piece at the same time, in different ways, and a policy covering your owned inventory does not automatically cover someone else's inventory sitting in the same case. A jewelers block policy is the product that explicitly extends to memo, consignment and customers' goods; check that yours does before you assume it.
You owe a report, not just a payment. The obligation on sale is to tell the supplier and settle within terms — commonly 15 to 30 days, which is what JVC and the trade recommend. A piece that sells and does not get reported is not a cash-flow win. It is the beginning of a dispute, and it is the kind of dispute that ends a supply relationship.
It ages too. Goods that should have gone back three months ago are occupying case space, insurance capacity and your relationship's goodwill while earning nobody anything.
Where the two sides meet: one counterparty, one net position
The businesses that handle this best stop thinking about memo as two separate processes and start thinking about counterparties.
Plenty of businesses are on both sides with the same firm. A wholesaler holds stones from a dealer while placing finished goods with retailers. A retailer holds supplier product while sending pieces out to a second location, a show, or an outside bench. When goods, invoices and payments are all moving in both directions with one counterparty, the only number that means anything is the net position — and the only way to get a net position is to run both sides on the same ledger.
This is also what ends most disputes. Every disagreement about memo has the same shape: two ledgers and two memories. The resolution is not a better argument, it is a single shared record that both sides can open. When the retailer can look at the same statement the supplier is reading from, "I paid for those" becomes a five-second check instead of a ten-minute conversation.
The reconciliation both sides keep getting wrong
Reconcile per line, not per document.
The standard failure: a ten-line memo, the retailer keeps two pieces, returns eight, and pays for "the memo" at a figure that matches neither side's expectation. Eight returned should be checked against the tags. Two sold should be invoiced at the memo price on the sheet. The memo closes only when every line has a terminal status.
JVC's guidance builds monthly reconciliation into the agreement as an obligation rather than a courtesy, alongside segregated and tagged inventory so goods stay identifiable. Both of those exist to make line-level reconciliation possible. A reconciliation nobody agreed to is one that only happens when somebody is already worried.
Where Jewelia fits
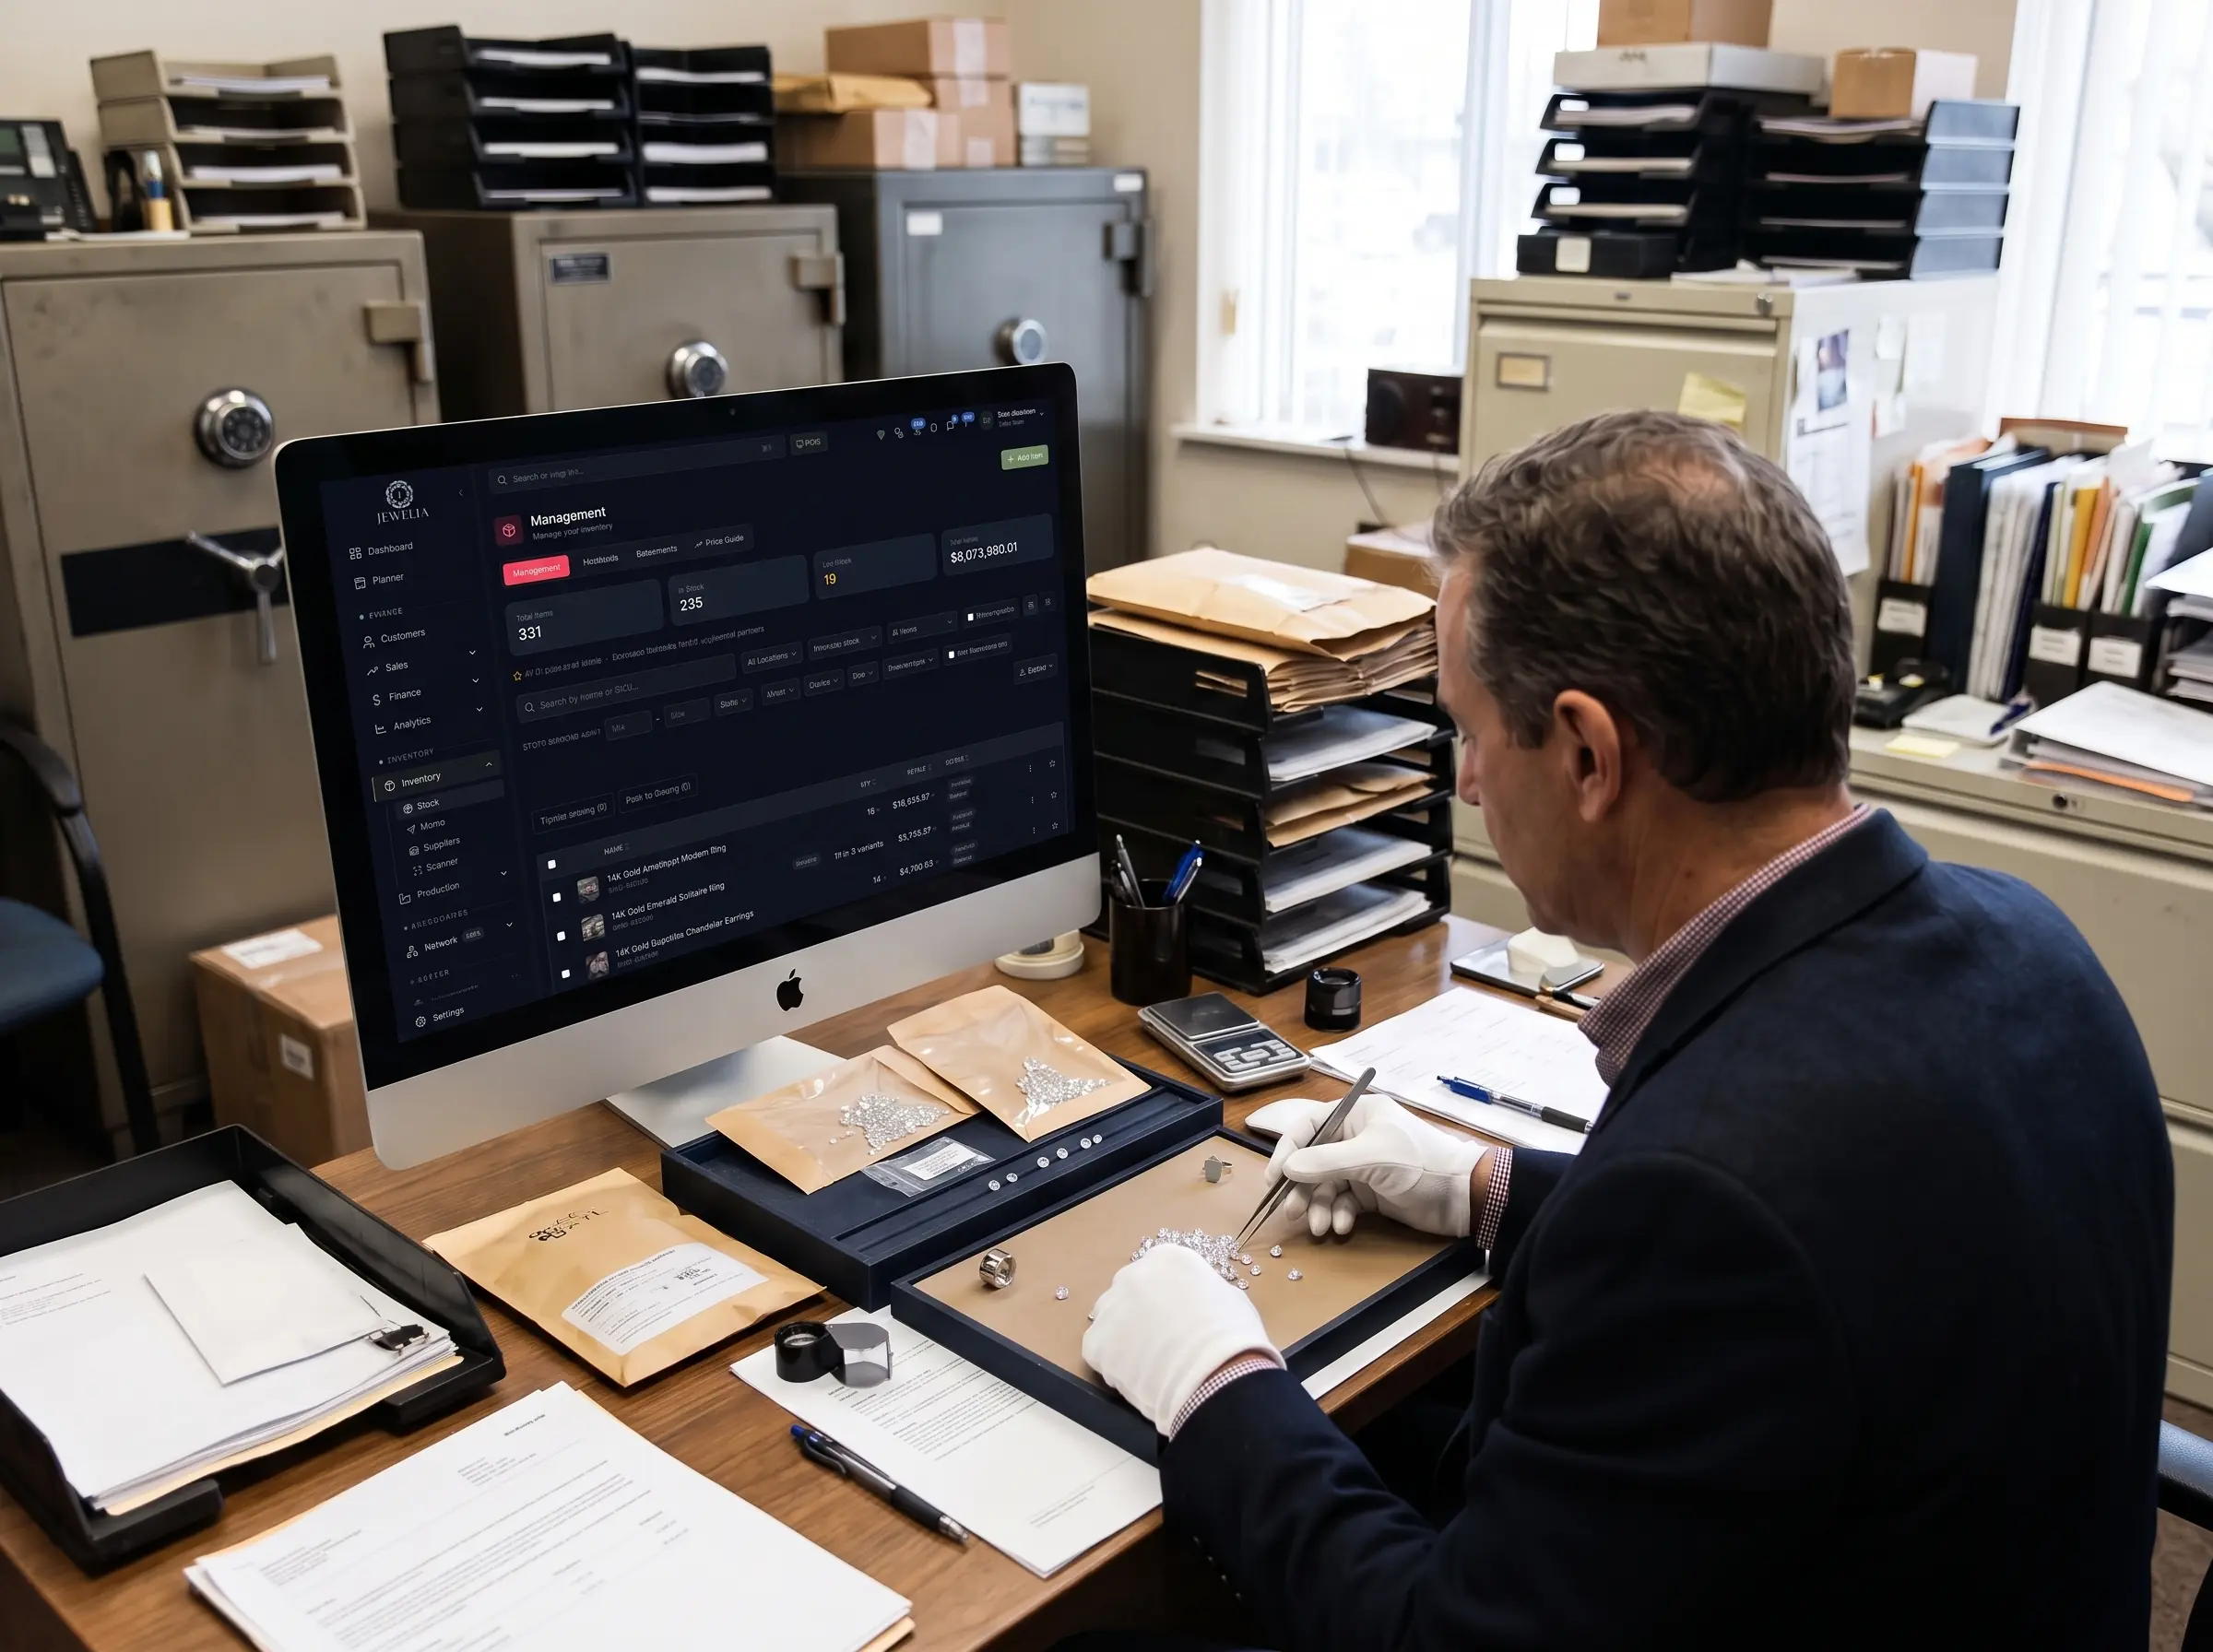
Memo & Ledger runs both directions on one set of records, which is the point. Memo out goes with terms, a due date and a PDF both sides receive, with every line tracked independently — still out, returned, or sold at the price it actually went for — and 30/60/90 aging with an overdue count per counterparty. Memo in tracks the same detail in reverse: what you hold, what is due back, what you have sold and what you owe.
Because both run on the same counterparty record, the Ledger nets them into a single balance per account with a live statement link the other side can open. Delivery is confirmed by a link that needs no account on the other end, ticking off line by line what actually arrived and attaching photos, so a discrepancy is logged against the memo rather than remembered differently later. And a sold line converts to an invoice in one click, which is the step most often skipped when it requires retyping.
Memo out and the Ledger are on the $179 Starter plan; memo in is on Professional. The wider system is in our memo tracking guide, and the accounting treatment in is consigned jewelry your inventory?.
Bottom line
Memo out is an asset at risk and unsecured credit — age it, perfect it, evidence it. Memo in is a liability in your case that must stay out of your stock valuation and inside your insurance. Run both on one ledger per counterparty, reconcile line by line, and the net position with anyone you trade with both ways becomes a number rather than an argument.
This article describes general US commercial practice and is not legal, accounting or insurance advice.
Frequently asked questions
- What is the difference between memo in and memo out?
- Memo out is goods you have sent to someone else to sell — still your property, still your asset, physically outside your control. Memo in is goods somebody has sent you — not your property, not your stock, physically in your case and your responsibility. Same parcel, opposite positions, completely different risks.
- Should memo-in goods appear in my inventory valuation?
- No. Under US GAAP the consignor retains control, and the goods remain on the consignor's balance sheet until control transfers. Treating goods you hold on memo as your own stock overstates your inventory value and distorts every ratio calculated from it, including turn and GMROI.
- Who insures goods held on memo?
- Whatever the agreement says, which is why so many memo agreements leave a gap. Both parties can hold an insurable interest in the same piece — the vendor owns it, the retailer has custody. A policy covering your owned inventory does not automatically extend to someone else's goods in your case. A jewelers block policy is the product that explicitly covers memo, consignment and customers' goods.
- Which side carries more risk?
- The supplier carries the financial exposure. The Jewelers Vigilance Committee's senior counsel describes the supplier as in effect lending the merchant the cost of the goods. But the retailer carries custody risk, potential liability for loss or damage, and the reconciliation obligation — and if the retailer fails, unperfected consigned goods become part of its bankruptcy estate, which hurts the supplier and complicates the estate.
- Do I need to age memo in as well as memo out?
- Yes. Memo in that ages silently is how a retailer ends up with a supplier statement they cannot argue with, and how goods that should have gone back months ago are still sitting in a case earning nothing while occupying the space and the insurance.
- Can the same business run both?
- Constantly. A wholesaler places goods with retailers while holding stones from dealers. A retailer holds supplier goods while sending pieces out to a second location or a show. Running both sides on one system with one set of records is the only way the net position with any given counterparty is ever a single number.
Stop reading, start clicking.
Open a live Jewelia company with real inventory, memo, jobs and reports already in it. One work email, no card, no sales call, nothing to install.